GET IN TOUCH
- Please wait...

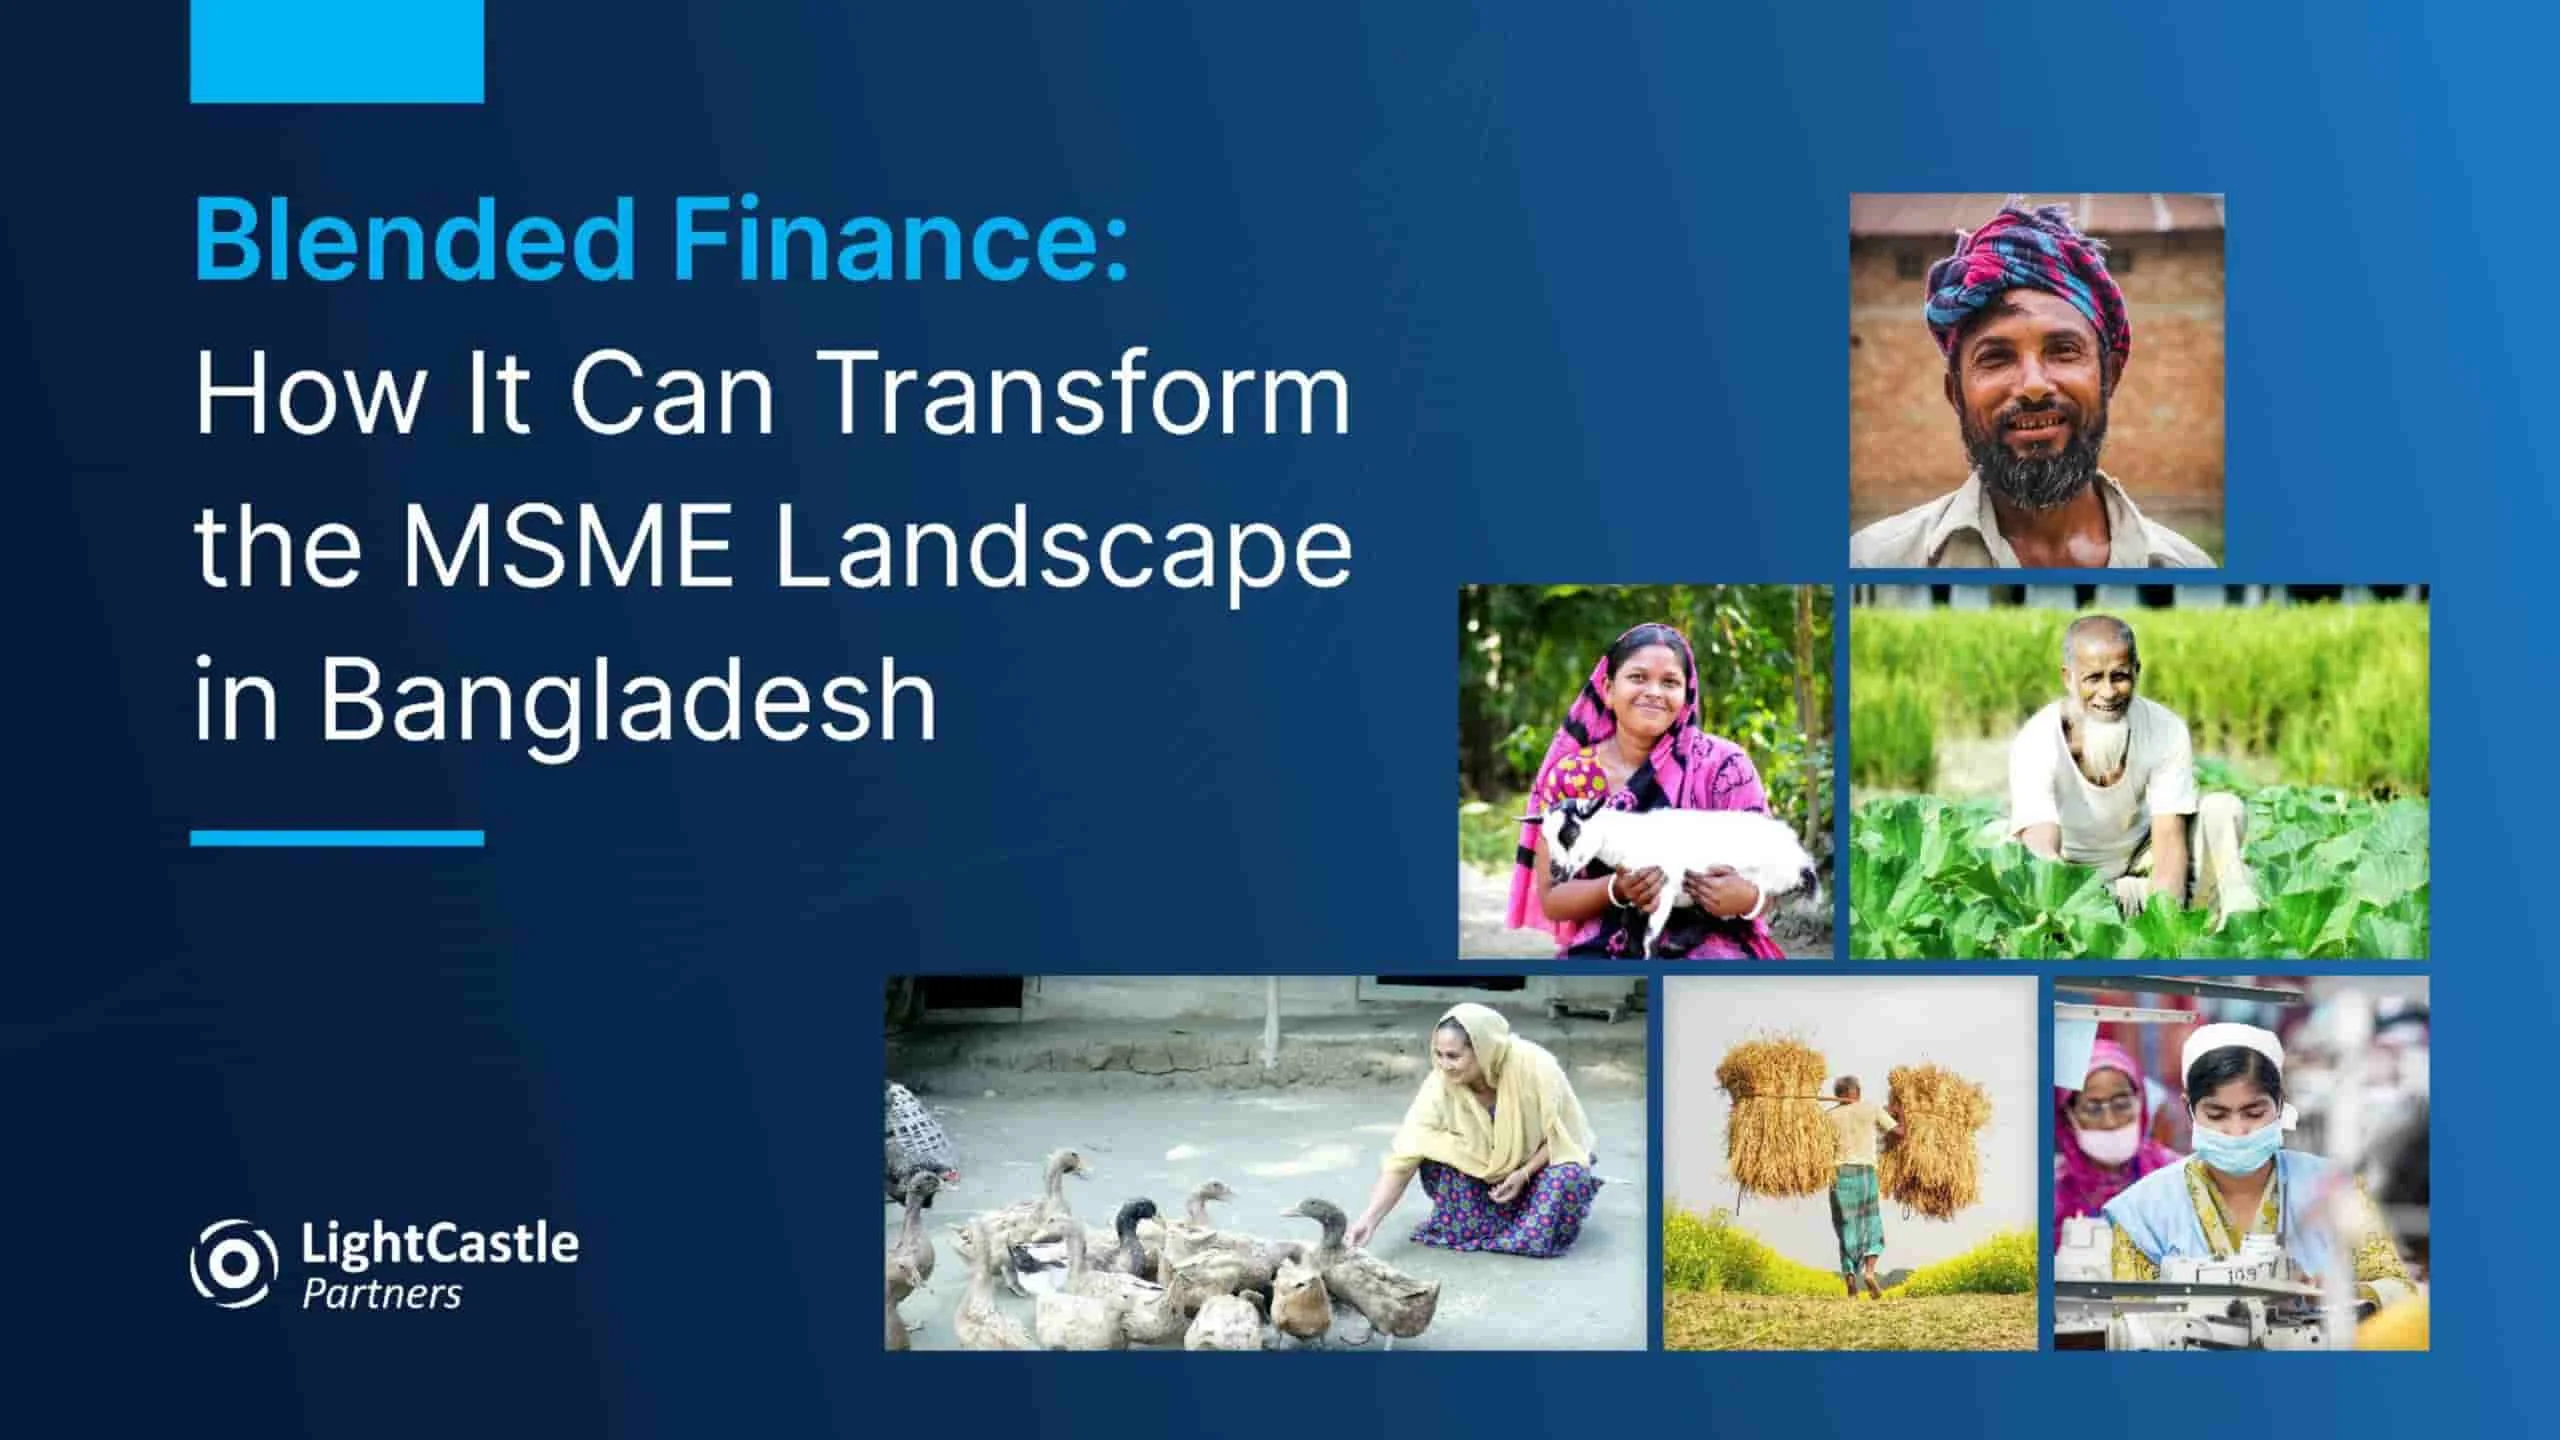
Bangladesh has built a dynamic entrepreneurial ecosystem. From small manufacturers and agricultural enterprises to technology-enabled businesses, SMEs drive employment and economic activity. Yet access to suitable capital remains one of the most persistent barriers to their growth.
The numbers tell an important story. Bangladesh has approximately 11.7 million non-farm economic units, 95% of which are cottage or micro enterprises. SMEs contribute around 27% of GDP, compared with 60% in China and 61% in Indonesia. IFC estimates the country’s MSME financing gap at USD 73.5 billion—nearly three-quarters of potential demand. As of March 2026, cottage, micro, small and medium enterprises received only 15.9% of bank lending, against a 25.5% national target.
We have an expanding entrepreneurial ecosystem, but our financing architecture has not evolved sufficiently to support it.
Traditional lending remains heavily dependent on collateral, historical financial statements and established banking relationships. Many promising enterprises lack these, even when their businesses have customers, revenues and growth potential. Increasing lending targets alone will not solve this problem. We need to rethink how capital is structured, how risks are shared and how businesses are assessed.
This is where catalytic and patient capital can play an important role. Through blended finance, development partners and impact investors can provide guarantees, technical assistance, concessional funding and outcome-based incentives to reduce risks and mobilise commercial investment. Patient capital also gives enterprises time to strengthen operations and scale, rather than forcing them into financing products designed for short-term needs.
Initiatives such as the proposed Bangladesh Impact Fund illustrate this approach: combining catalytic support with commercial investment to provide growth capital to promising businesses, with measurable development outcomes alongside financial returns.
Technology offers another important part of the solution. The City Bank–bKash digital nano-loan partnership demonstrates what can happen when transaction histories and digital credit assessment complement traditional banking methods.
By July 2026, the partnership had disbursed more than USD 811 million in cumulative loans to approximately 3.5 million customers across 31.9 million loans. Its reported non-performing and written-off amount was around 0.5% of cumulative disbursements. The average loan was approximately USD 24, highlighting the small-ticket nature of the model.
Digital nano loans are not a substitute for long-term SME investment. But they demonstrate how digital data can help institutions reach customers without conventional collateral or extensive paperwork. With appropriate consent, safeguards and responsible underwriting, business transaction data and cash-flow patterns could support more relevant credit scoring for SMEs.
For Bangladesh, the opportunity lies in connecting three elements: patient capital, innovative financial institutions and digital infrastructure. Catalytic capital can share early risks. Technology can reduce information gaps and transaction costs. Banks and investors can then offer products aligned with the real needs of growing businesses.
Finance alone will not be enough. Enterprises also need stronger governance, financial management, market access and the capabilities to absorb capital productively. Having worked closely with entrepreneurs across Bangladesh, I believe the challenge is not a shortage of ambition. It is building an ecosystem that consistently translates that ambition into scalable businesses.
Bangladesh pioneered microfinance. Our next opportunity is to build an equally inclusive financing ecosystem that helps small businesses become the growth engines of tomorrow.
This article was authored by Bijon Islam, Co-founder and CEO of LightCastle Partners. For further clarification, please contact: [email protected].
Our experts can help you solve your unique challenges
Stay up-to-date with our Thought Leadership and Insights