GET IN TOUCH
- Please wait...

For more than a decade, Bangladesh’s development story has been closely tied to the strength of its workforce. Behind the country’s economic growth and transformation are millions of workers, particularly those in blue-collar jobs, who have kept factories running, built industries, supported businesses, and carried the country’s economy forward.
Figure 1: Sankey Diagram of Share of Blue-Collar Workers in Bangladeshi
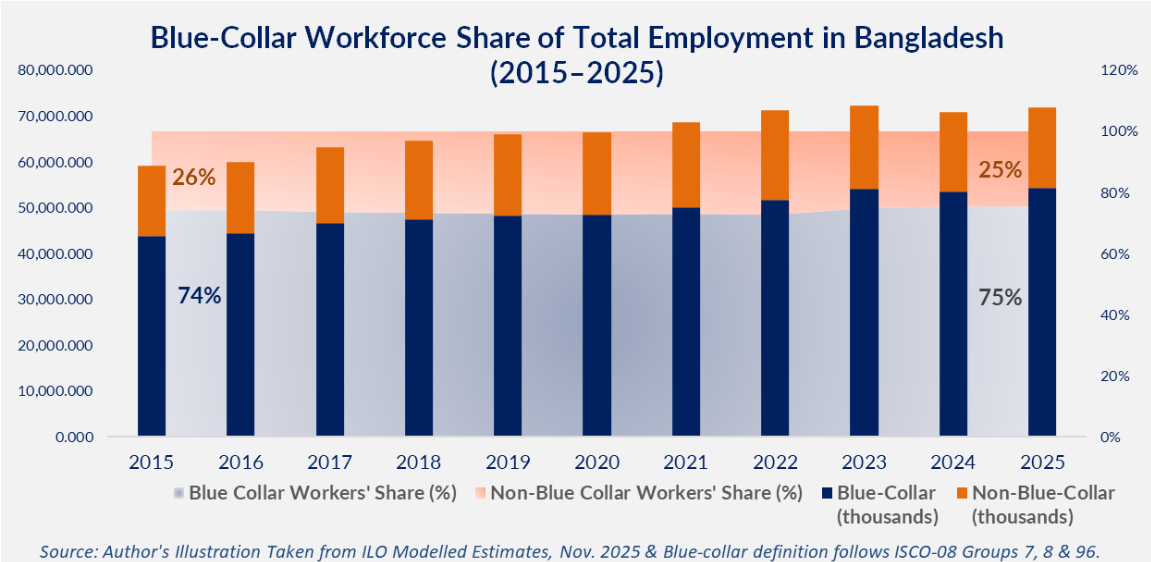
Note: Blue-Collar — ISCO-08 Groups 7, 8 & 96 (craft workers, operators & assemblers, elementary & agricultural occupations). Non-Blue-Collar — managers, professionals, technicians, clerical & service/sales workers.
Yet, the benefits of this growth have not resulted in more jobs for the very workers who have powered it. Bangladesh’s GDP grew at an average annual rate of approximately 6.5% between 2015 and 2023, while the industrial sector’s share of employment fell from 20.4% in LFS 2016–17 to 17.37% in LFS 2024.ii In absolute terms, industrial employment also declined even as output continued to grow, a phenomenon known as jobless growth, which is increasingly leaving Bangladesh’s blue-collar workers behind.
Bangladesh’s employment story becomes even clearer when we look at where workers are concentrated and how much value their work generates. Agriculture remains the country’s largest employer, absorbing 44.67% of total employed persons in 2024, while contributing only around 11.2%–11.7% of GDP.2 This imbalance has deepened as surplus workers have moved back to rural areas and into farming, where labour productivity has declined by an absolute 2.3% annually. Manufacturing tells a different story. Productivity has continued to rise, supported by automation and capital deepening, even as the sector’s share of employment has fallen.
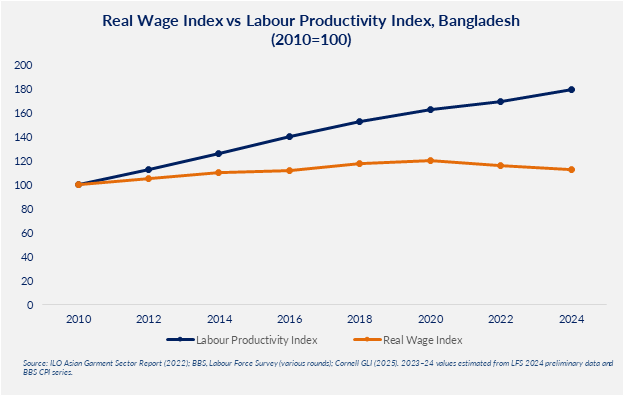
Yet, this productivity growth has not led to improvements in workers’ real wages. Persistent inflation has steadily eroded workers’ purchasing power, peaking at 9.86% in January 2024 and remaining above 10% during much of 2024, hampering the nominal wage gains.
Side by side, the absence of a mandatory annual wage adjustment or inflation-indexation mechanism for minimum wages exacerbates the situation. In the RMG sector, for instance, the entry-level minimum wage was set at BDT 12,500 per month in 2023, while trade unions estimate a living wage of around BDT 23,000, leaving workers with a gap of more than BDT 10,500 between what they earn and what they need for a decent standard of living.
Thus, technological advancement and automation may raise factory productivity and output, but where workers have limited collective bargaining power, a greater share of these gains risks accruing to capital owners as profits rather than reaching the workers whose labour continues to drive production.
Looking at developed economies such as the U.S., Bangladesh risks following a similar path of premature deindustrialisation. The two charts below tracking the United States from 1839 to 2016 show the structural sequence every industrialised economy has followed from agricultural to manufacturing to service sectors. Crucially, that manufacturing phase is what built real wages, organised labour, and the consumption base that made the shift to services sustainable. Deindustrialisation in the US came after manufacturing had done its work.
Our experts can help you solve your unique challenges
Stay up-to-date with our Thought Leadership and Insights